Is Pet Insurance Worth It? A Guide for Pet Owners
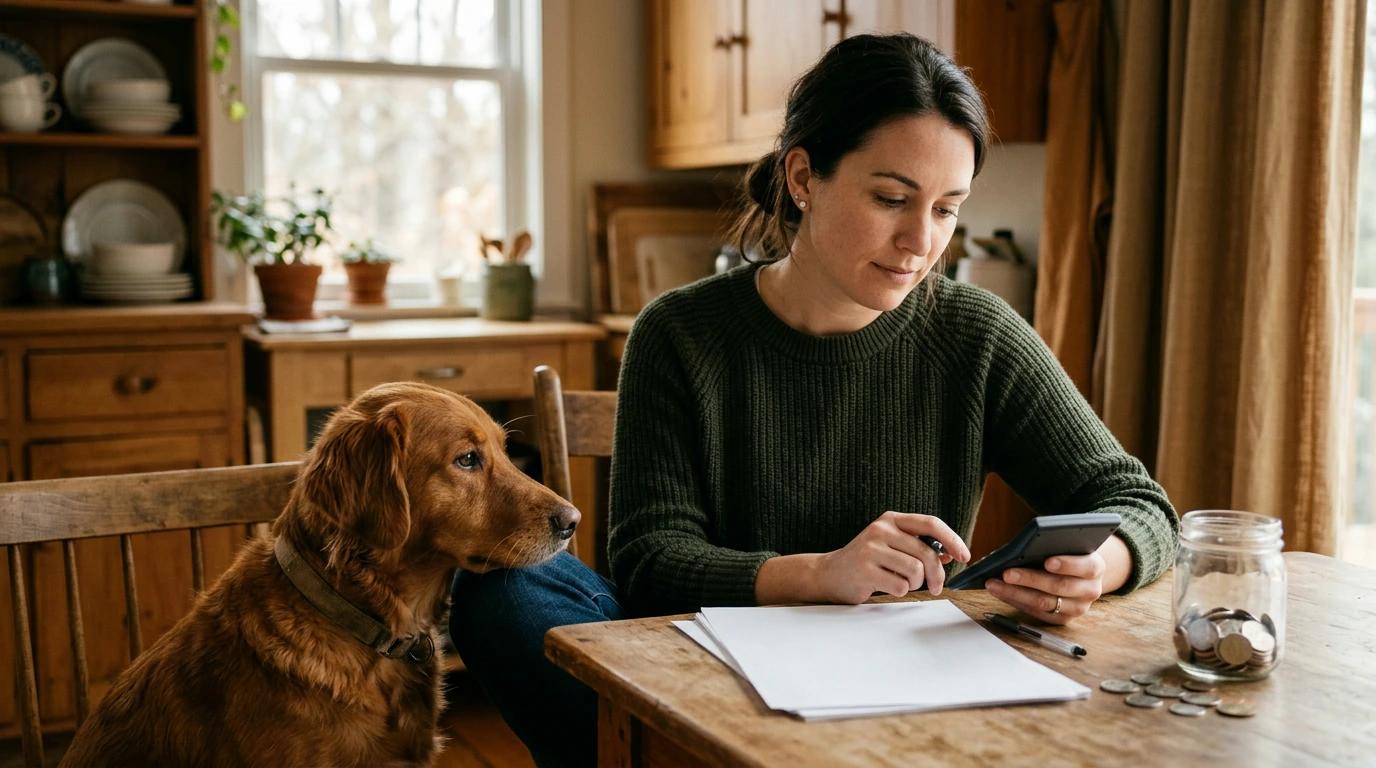
A surprise veterinary bill can arrive at the same time as rent, groceries, and other everyday expenses. Pet insurance is one way to prepare, but it isn’t automatically the right choice for every household. Its value depends on your pet, the policy’s terms, and how comfortably you could pay for unexpected care. For more guidance, see Is Pet Insurance Worth It?.
Our guide will help you compare coverage with the alternative of setting money aside, so you can make a decision that fits both your pet and your budget. For further reading, see Pet Insurance — Get Up to 90% Back on Vet Bills.
What Pet Insurance Can—and Cannot—Do
Pet insurance may help pay for covered veterinary care in exchange for a recurring premium. What it covers depends on the policy, so two plans with similar prices may offer very different protection.
An accident-only policy generally focuses on injuries from unexpected events, such as a broken bone. An accident-and-illness policy can also cover eligible treatment for illnesses. Optional wellness coverage, when available, may help with routine care such as exams or vaccinations. Review its cost and benefits separately from protection against major unexpected bills.
Insurance has limits. Policies may exclude certain treatments or conditions, and waiting periods can delay the start of coverage. Pre-existing condition rules can also restrict payment for health issues that appeared before coverage began. The American Veterinary Medical Association’s pet insurance resource offers additional guidance on evaluating policies.
The Costs to Compare Before Choosing a Policy
The monthly premium is only one part of the picture. Deductibles, reimbursement percentages, and coverage limits all affect what you may have to pay when your pet needs care.
| Policy term | What it means | Budget consideration |
|---|---|---|
| Premium | The recurring price of the policy | Include it in regular pet-care spending. |
| Deductible | The eligible amount paid before reimbursement begins | Check whether it applies annually or per condition. |
| Reimbursement percentage | The share of eligible costs the insurer pays | You generally pay the remaining share. |
| Coverage limit | The maximum the insurer will pay under the policy terms | A low limit may leave more of a large bill to you. |
Many insurers reimburse eligible expenses after you pay the veterinarian and submit a claim, although payment arrangements vary. You may still need access to money or credit when treatment is due, even if you expect reimbursement later.
Also ask how the insurer calculates reimbursement. For example, a stated percentage may apply to eligible charges rather than the entire bill. Expenses excluded by the policy can remain your responsibility.
When Pet Insurance May Be Worth It
Coverage may be appealing if a large, unexpected vet bill would be difficult to absorb but a predictable premium fits your budget. It can help transfer some financial risk to an insurer, subject to the policy’s deductible, limits, and exclusions.
Compare that cost with building a dedicated pet emergency fund. Savings can be used flexibly, including for expenses a policy excludes, and any unused balance remains yours. The trade-off is that a new fund may not yet contain enough to cover a major bill.
You can also use both: insurance for eligible larger expenses and savings for deductibles, excluded care, or bills you must pay before reimbursement. Whatever approach you choose, avoid assuming insurance will save you money. You may pay more in premiums than you receive in reimbursements, particularly if your pet needs little covered care.
Questions to Ask Before You Buy
Before choosing a plan, request quotes using your pet’s details and compare the actual policy documents—not just the advertised price. Ask each insurer:
- How do you define a pre-existing condition, and are there any exceptions?
- When do accident and illness coverage begin?
- Which treatments, conditions, and fees are excluded?
- How are eligible charges and reimbursement amounts calculated?
- Is the deductible annual or per condition, and what limits apply?
- How long do I have to submit a claim?
- What are the renewal terms, and how might premiums change?
Keep the answers alongside your quotes. A less expensive plan may suit you, but only if you’re comfortable with the expenses it leaves uncovered.
Explore the Protecting Paws Guide
Our Protecting Paws Without Breaking the Bank guide is a starting point for pet owners weighing whether insurance is worthwhile. It costs $6.99 USD; that is the price of the guide, not an insurance premium or policy.
Visit the product page before comparing insurance options. If you’re also planning a trip and want to explore ways to manage travel spending, our travel deals digital ebook is a separate resource.
FAQ
Is pet insurance worth it for a healthy pet?
A healthy pet can still have an unexpected accident or illness. Whether insurance is worthwhile depends on the premiums, exclusions, and your ability to pay unexpected bills.
Does pet insurance cover pre-existing conditions?
Pre-existing conditions are commonly excluded, but definitions and exceptions vary by insurer and policy. Review the policy’s terms before enrolling.
Is an emergency fund better than pet insurance?
An emergency fund offers flexibility, while insurance may help protect you from large covered bills. Some owners use both to prepare for deductibles, exclusions, and unexpected care.



Leave a comment